

OneBlinc - Financial tools
4.6

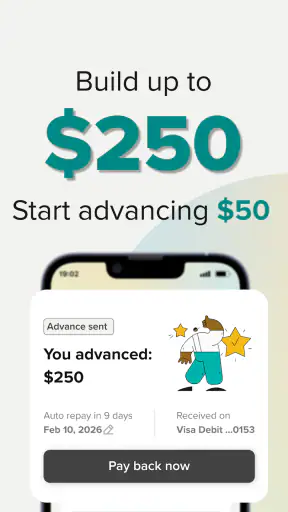
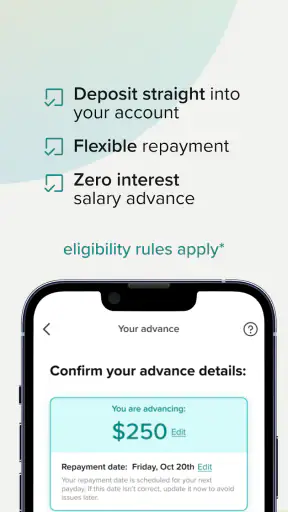
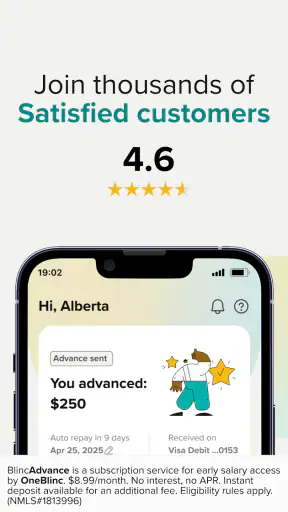
I tried OneBlinc as a finance app with a very specific purpose: helping users access part of their earned wages and send the money to a linked account. That focus makes it easier to understand than a general budgeting app, but it also means its usefulness depends heavily on whether you actually need short-term access to income before your usual payday.
The app is developed by OneBlinc and is available free of charge. It is listed for Everyone, so its presentation is aimed at a broad audience rather than a specialist financial market. The central promise is access to wages of up to $250 through a linked account, which puts the service closer to an earned-wage-access tool than to a full banking replacement.
My overall impression is that it can be practical in a tight week, especially when a small unexpected expense arrives before payday. I would not treat it as a complete money-management system, though. Its value comes from solving a narrow cash-flow problem, not from replacing savings, budgeting, or long-term financial planning.
How OneBlinc fits into everyday money management
A focused tool rather than a complete banking app
When I open a finance app, I usually want to know immediately what problem it solves. Here, the answer is fairly direct: OneBlinc is built around wage access. Instead of asking users to apply for a conventional personal loan or rely on a credit card, it centers the experience on moving available wages to a linked account.
That distinction matters. A traditional bank app may show balances, transfers, bills, and account history, while a budgeting app may categorize spending and set targets. OneBlinc’s role is much narrower. I see it as a short-term bridge for people whose income is already being earned but is not yet available through their normal pay cycle.
The free price is an important part of the decision. I can evaluate the app as free access rather than as a purchase that must justify a subscription or upfront payment. At the same time, free access should not automatically be confused with free money. Anyone considering a wage-access service should read the in-app terms carefully before confirming a transaction, including any conditions connected with eligibility, repayment, timing, or account linking.
That is the first practical lesson I would give a friend: install it because the workflow may be useful, not because the word “free” removes the need to understand the transaction. A free app can still connect you to a financial service with its own rules.
What the current release tells me about the product
The current version is 7.12.0, and the app supports Android 7.0 or later. That makes it accessible to people who keep an older Android phone instead of upgrading frequently. In daily use, compatibility is easy to overlook, but it can decide whether a finance tool is available when someone actually needs it.
OneBlinc was released on February 18, 2025, so I would approach it as a relatively recent product rather than a long-established personal finance suite. The app has passed the early discovery stage, with over one hundred thousand installs and an average rating of 4.6 from around 4,800 ratings. Those figures suggest meaningful adoption and generally positive user response, although they do not tell me whether the app will fit every employment or banking situation.
The review count is also substantial enough to show that people are actively using and evaluating it. Still, ratings are a starting point, not a guarantee. Financial apps are especially sensitive to individual circumstances: an experience that works smoothly for one person can be less useful for someone with a different employer, pay schedule, or linked account.
The practical workflow I would use
I would begin by installing the app only on my personal device and checking the account-linking screens slowly. In a financial product, rushing through setup is a mistake. I would verify that the account shown is the one I intend to use, confirm the amount before submitting a request, and keep the confirmation details for my own records.
A realistic scenario would be an unexpected prescription, a necessary trip to work, or a small household repair arriving several days before payday. In that situation, the ability to access earned wages can be more relevant than opening a new credit card. The app’s advantage is speed of purpose: it is aimed at a specific cash-flow gap instead of surrounding the user with unrelated financial tools.
I would also decide in advance how the amount fits into my next pay cycle. If taking money early leaves too little for rent, groceries, or automatic bills later, the immediate relief may create a second problem. The useful question is not simply “Can I access this money?” but “Will accessing it now make the next few days easier overall?”
Where the free access creates value
Because the app itself is free, the entry barrier is low. I do not have to pay merely to explore whether the workflow suits me. That is valuable for someone who wants to understand the process before relying on it, provided they review every transaction screen rather than assuming all related services have identical costs.
The main value is flexibility. A fixed payday works well when expenses arrive predictably, but real life is less tidy. A small gap can lead to overdraft charges, late payments, or missed transport. Access to earned wages may help a user avoid one of those problems. I would consider that a targeted convenience, not a reason to use the service routinely for discretionary spending.
There is also a psychological benefit to a focused interface. A person under financial pressure does not necessarily need charts, categories, and long-term dashboards in that moment. They may need to understand whether a wage-access request is possible and where the funds will go. OneBlinc’s narrow purpose can make it less distracting than a full personal finance platform.
However, the value depends on the user’s actual eligibility and circumstances. A free download does not guarantee that every worker will receive the same result. I would check the app’s own flow for the requirements that apply to me, and I would not plan an urgent payment around an assumption that access will always be available.
Three details that deserve more attention than the headline
First, the linked-account step is not just a technical formality. It determines where the money is directed, so I would treat it like setting up a bank transfer rather than like signing into a casual shopping app. I would avoid linking an account I rarely monitor and would check the destination before each important request.
Second, the maximum access amount should not become a personal target. Up to $250 can sound like a useful cushion, but the right amount is the smallest amount that solves the immediate need. Requesting less can make it easier to preserve room for upcoming essentials and reduces the chance that a temporary solution becomes part of a repeating cycle.
Third, I would use the app alongside a simple calendar note. After requesting funds, I would write down the amount and the expected effect on my next payday. This small habit turns the app from an impulse button into a controlled cash-flow tool. It also helps reveal whether I am using wage access for rare emergencies or depending on it every pay period.
A fourth useful habit is to compare the request with the alternatives before confirming it. If moving a bill by a day, using an existing emergency fund, or asking a provider for a payment arrangement solves the problem without affecting the next paycheck, that option may be better. OneBlinc is most useful when it fills a genuine timing gap, not when it substitutes for planning that could be handled more cheaply or safely.
Tradeoffs compared with the usual alternatives
Compared with a credit card, wage access may feel more direct because it is connected to earned income rather than a revolving credit limit. The tradeoff is that it can reduce what is available in a future pay cycle. A credit card can spread repayment differently, but it may also carry interest or encourage a longer debt balance. I would choose based on the full cost and repayment effect, not on convenience alone.
Compared with an overdraft, accessing wages early may be more intentional than allowing an account to fall below zero. Yet the better option depends on the terms shown to the user and the timing of the need. I would never assume that one route is automatically cheaper simply because it is presented inside a finance app.
Compared with a personal loan, OneBlinc appears designed for a much smaller and more immediate need. That can be an advantage when borrowing a larger amount would be excessive. On the other hand, someone facing a major, ongoing financial problem needs a broader plan. A wage-access request cannot solve a persistent gap between income and essential expenses.
Compared with a savings account, it is a fallback rather than a replacement. Savings provide money without reducing a future paycheck, while wage access brings future income forward. If I had an emergency fund available, I would usually examine that first. The app is more compelling for someone who has earned the money but is temporarily waiting for the normal payment date.
Compared with a budgeting app, OneBlinc answers a different question. Budgeting software helps me decide where money should go; this app helps address when some income becomes available. Using both could make sense, but OneBlinc alone will not show me whether my spending habits are sustainable.
Who is likely to get the most from it
I would recommend trying OneBlinc to a worker who experiences occasional timing problems between earned wages and necessary expenses. It may suit someone who wants a focused Android tool, has a compatible device, and prefers checking a wage-access option before turning to a credit card or loan.
It may also help people who dislike complicated financial products. The app’s purpose is easier to explain than a full lending marketplace: access part of earned wages and send the funds to a linked account. That simplicity can be valuable when the user is stressed and needs to make a quick but informed decision.
I would be more cautious for anyone who already struggles to cover essentials from one payday to the next. In that case, early access can mask the underlying problem while making the next pay period tighter. A conversation with a financial counselor, a revised bill schedule, or a basic spending plan may offer more lasting value than repeated requests.
I would also skip it as a primary solution if I need investment tools, detailed expense tracking, savings goals, or ordinary day-to-day banking features. Those needs call for a broader finance app or a bank account with stronger money-management tools. OneBlinc’s strength is its narrow use case, and that is also its clearest limitation.
Questions I would settle before relying on it
“Will I receive money every time I request it?” I would not assume that. I would follow the app’s eligibility and account-linking process at the moment I need the funds. A responsible plan leaves a backup option instead of depending on an untested request for a time-sensitive bill.
“Is the free app the same as a free transaction?” Those are different questions. The download is free, but I would inspect the final request screen and the applicable terms for any transaction-specific conditions before proceeding. That is especially important when the amount is needed for an essential payment.
“Can it replace my bank?” I would say no. The app is better understood as a financial tool for wage timing. I would keep using my regular bank for ordinary account management and use OneBlinc only when its specific function makes sense.
“What amount should I request?” My answer is the minimum needed for the immediate expense, not automatically the maximum. I would compare that amount with the next payday’s bills and leave enough room for essentials. The convenience is strongest when the request is deliberate.
“What if my situation changes?” I would review linked-account details, employment information, and the expected repayment or pay-cycle effect before making another request. Financial apps should be revisited when income, bank accounts, or regular expenses change; a setup that was suitable last month may not be suitable now.
My buy-or-skip verdict
Since OneBlinc is free to access, I see little reason to reject it solely because of price. For the right user, it offers a focused way to explore wage access without paying upfront for the app itself. The meaningful decision is not whether to buy it, but whether its transaction terms and effect on the next payday fit the situation.
I would install it if I occasionally face a small, urgent gap between earning money and receiving it, and I would test the setup before an emergency occurs. I would keep the first request conservative, verify the linked account, and record how the next pay cycle is affected. Those steps turn a convenient feature into a more responsible workflow.
I would skip relying on it if I need a complete budget, long-term debt help, savings management, or a dependable answer to recurring shortfalls. In those cases, a bank, budgeting tool, savings plan, or professional financial guidance may be a better match.
My final view is favorable but measured: OneBlinc is most valuable as an occasional cash-flow bridge, not as extra income. Its free availability, focused purpose, broad Everyone rating, and positive reception make it worth investigating for eligible users. Just keep the central tradeoff in sight—bringing wages forward can solve today’s problem while changing the shape of the next paycheck.
4.6
672.00 Reviews
Pros
- Builds credit history through eligible bill payments and spending.
- Early direct-deposit access can help manage short-term cash flow.
- Clear repayment schedules make borrowing costs easier to track.
- Identity verification and account alerts add useful security controls.
- Useful budgeting tools help monitor recurring expenses and cash reserves.
Cons
- Availability and features may vary by state and eligibility.
- Some services require a paid membership or additional fees.
- Credit-building benefits depend on timely payments and reported accounts.
- Cash advances may encourage repeated borrowing between paychecks.
- Linking bank accounts may raise privacy concerns for some users.


